
Persistent knee pain can significantly diminish your quality of life, making even simple tasks like walking or climbing stairs a challenge. At Suvira Hospital, Jaipur, our orthopedic department specializes in comprehensive care ranging from conservative therapies to advanced joint replacement surgeries to help you walk pain-free again.Understanding the Impact of Chronic Knee PainKnee pain is one of the most common orthopedic complaints among adults in Jaipur. Whether it is caused by a sudden sports injury or the gradual wear and tear of aging, the impact on your daily routine can be profound. At Suvira Hospital, we believe that understanding the root cause of your discomfort is the first step toward effective recovery. Our orthopedic specialists utilize state-of-the-art diagnostic tools to pinpoint the exact issue, ensuring a personalized treatment plan for every patient.Common Causes of Knee PainThe knee is a complex joint that bears the weight of your entire body. Because of its complexity, several factors can lead to pain and dysfunction.1. OsteoarthritisOften referred to as 'wear and tear' arthritis, osteoarthritis is the leading cause of chronic knee pain in older adults. It occurs when the protective cartilage that cushions the ends of your bones wears down over time, leading to bone-on-bone friction, inflammation, and stiffness.2. Ligament Injuries (ACL/MCL)Common among athletes and active individuals, injuries to the Anterior Cruciate Ligament (ACL) or Medial Collateral Ligament (MCL) can cause immediate instability and sharp pain. These often require specialized orthopedic intervention to restore full function.3. Meniscus TearsThe meniscus acts as a shock absorber between your shinbone and thighbone. A sudden twist or pivot can tear this cartilage, causing swelling and a sensation that the knee is 'locking' or 'giving way.'4. Bursitis and TendonitisInflammation of the small fluid-filled sacs (bursae) or the tendons surrounding the knee joint can lead to localized pain, often exacerbated by repetitive movements.Non-Surgical Treatment Options at Suvira HospitalSurgery is not always the first answer. At Suvira Hospital, our orthopedic team prioritizes conservative management whenever possible. Our goal is to reduce inflammation and strengthen the joint through non-invasive means.Physical Therapy: Custom exercise programs designed to strengthen the quadriceps and hamstrings, which provide essential support to the knee joint.Lifestyle and Weight Management: Reducing body weight significantly lowers the pressure on the knees, often providing immediate relief from arthritic symptoms.Medication Management: Use of anti-inflammatory drugs and specialized pain relief protocols to manage acute flare-ups.Injections: We offer advanced intra-articular injections, including Hyaluronic acid (viscosupplementation) and Platelet-Rich Plasma (PRP) therapy, to promote healing and lubrication within the joint.When is Joint Replacement Necessary?When conservative treatments no longer provide relief and the pain interferes with your sleep or basic mobility, Total Knee Replacement (TKR) or Partial Knee Replacement may be recommended. Modern joint replacement surgery at Suvira Hospital is a highly successful procedure designed to replace the damaged surfaces of the knee with durable artificial components.The Benefits of Advanced SurgeryOur surgeons utilize minimally invasive techniques, which typically result in smaller incisions, less blood loss, and a faster return to daily activities. By using high-grade implants and precision alignment tools, we ensure that the new joint feels natural and lasts for many years.Recovery and Rehabilitation: Your Path Back to MobilityThe success of a knee procedure depends heavily on the post-operative phase. At Suvira Hospital, we provide a comprehensive rehabilitation program that begins almost immediately after surgery. Our physiotherapists work closely with patients to encourage early movement, which is crucial for preventing stiffness and blood clots.Most patients are able to walk with assistance within 24 hours of surgery. Over the following weeks, dedicated therapy sessions help restore the range of motion and build the muscle strength necessary for independent living.When to See an Orthopedic SpecialistIf you are experiencing any of the following 'red flag' symptoms, it is time to consult with the experts at Suvira Hospital:Inability to bear weight on the affected leg.Visible deformity in the knee joint.Severe swelling that does not improve with rest and ice.A 'locking' sensation or inability to fully straighten the leg.Pain that persists even while resting or at night.Why Choose Suvira Hospital, Jaipur?Suvira Hospital stands as a beacon of orthopedic excellence in Jaipur. Our department is equipped with modern modular operating theaters, advanced imaging technology (X-ray, CT, and MRI), and a team of compassionate surgeons dedicated to patient-centric care. We don't just treat the joint; we treat the person, ensuring you receive the emotional and physical support needed for a successful recovery.Book an appointment with our Orthopedic Department today and take the first step toward a pain-free life.This article is for educational purposes only and is not a substitute for professional medical advice. Please consult a qualified doctor for diagnosis and treatment.Frequently Asked QuestionsHow long does recovery take after a knee replacement?Most patients can return to light daily activities within 3 to 6 weeks. However, full recovery and the ability to engage in more strenuous activities may take 6 months to a year, depending on the patient's overall health and commitment to physical therapy.Are there any risks associated with knee surgery?As with any major surgery, there are risks such as infection, blood clots, or implant wear. However, at Suvira Hospital, we follow strict sterilization protocols and use advanced surgical techniques to minimize these risks significantly.Can knee pain be cured without surgery?Many cases of knee pain, especially those caught early, can be managed effectively through physical therapy, weight loss, and medication. Surgery is typically reserved for severe cases where non-surgical methods have failed to provide relief.
Read Article
Chronic joint pain can significantly impact your quality of life, making simple daily tasks feel like a struggle. At Suvira Hospital in Jaipur, we believe that understanding the root cause of your discomfort is the first step toward reclaiming your mobility and comfort.What Causes Chronic Joint Pain?Joint pain is a common complaint that can affect any part of your body, from your feet and ankles to your shoulders and hands. While occasional aches are normal, persistent pain that lasts for weeks or months requires professional evaluation. The most common culprits include:Osteoarthritis: The most common form of arthritis, caused by the wear and tear of joint cartilage over time.Rheumatoid Arthritis: An autoimmune disorder where the body attacks its own joint tissues.Bursitis: Inflammation of the small, fluid-filled sacs that cushion the bones, tendons, and muscles near your joints.Gout: A form of arthritis characterized by severe pain, redness, and tenderness in joints, often the big toe.Injuries: Previous fractures, ligament tears, or repetitive strain injuries that never fully healed.The Impact on Daily LifeWhen joint pain becomes chronic, it often leads to a cycle of inactivity. Patients may avoid movement to prevent pain, which in turn leads to muscle weakness and stiffness, ultimately worsening the joint condition. Breaking this cycle is essential for long-term health.Diagnostic Approaches at Suvira HospitalTo provide the best care, our orthopedic specialists use advanced diagnostic tools to pinpoint the exact source of your pain. This may include:Digital X-rays to assess bone health and joint space.MRI scans for detailed views of soft tissues, ligaments, and cartilage.Blood tests to rule out inflammatory or autoimmune conditions.Physical examinations to test range of motion and joint stability.[IMAGE_PLACEHOLDER_1: A clean, modern medical illustration showing the anatomy of a healthy knee joint versus an arthritic knee joint, placed after the diagnostic approaches section.]Modern Treatment OptionsTreatment for joint pain is highly personalized. At Suvira Hospital, we prioritize conservative, non-surgical methods before considering invasive procedures.Non-Surgical ManagementPhysical Therapy: Tailored exercise programs to strengthen muscles around the joint and improve flexibility.Medication Management: Anti-inflammatory drugs or pain relief therapies to manage symptoms.Lifestyle Modifications: Weight management and ergonomic adjustments to reduce stress on weight-bearing joints.Surgical InterventionsWhen conservative treatments are no longer effective, our orthopedic surgeons offer state-of-the-art surgical solutions, including minimally invasive arthroscopy and joint replacement surgeries, designed to get you back on your feet faster.[IMAGE_PLACEHOLDER_2: A photo of a physical therapist assisting a patient with rehabilitation exercises in a modern clinic setting, placed after the treatment section.]When to See an Orthopedic SpecialistYou should schedule an appointment with our orthopedic department if you experience any of the following:Pain that prevents you from performing daily activities.Visible deformity in the joint area.Significant swelling, redness, or warmth around the joint.Pain that persists despite rest and over-the-counter medication.Difficulty bearing weight on a specific limb.ConclusionYou don't have to live with chronic joint pain. With the right diagnosis and a comprehensive treatment plan, you can regain your mobility and enjoy a pain-free life. Our team at Suvira Hospital is dedicated to providing compassionate, evidence-based care to the people of Jaipur. Book an appointment with our Orthopedic Department today to start your journey toward recovery.Frequently Asked QuestionsIs surgery always necessary for joint pain?No. Surgery is typically considered only after conservative treatments like physical therapy, medication, and lifestyle changes have failed to provide relief.How can I prevent joint pain from getting worse?Maintaining a healthy weight, staying physically active with low-impact exercises, and ensuring proper posture can significantly reduce stress on your joints.Does Suvira Hospital offer post-surgery rehabilitation?Yes, we provide comprehensive post-operative rehabilitation services, including specialized physiotherapy, to ensure a smooth and effective recovery.
Read Article
Entering your 40s is a pivotal time to prioritize cardiovascular wellness and understand your personal risk factors. At Suvira Hospital, Jaipur, we provide comprehensive screenings and expert guidance to help you maintain a strong heart through lifestyle modifications and advanced medical care.Why Your 40s Are a Critical Decade for Heart HealthFor many, reaching the age of 40 is a significant milestone. However, from a physiological perspective, it is also the decade where the cumulative effects of lifestyle choices, genetics, and aging begin to manifest in the cardiovascular system. During this period, metabolism often slows down, hormonal balances shift, and the risk of developing conditions like hypertension or high cholesterol increases significantly.At Suvira Hospital in Jaipur, our cardiology department emphasizes that prevention is not just about avoiding illness; it is about optimizing your body's most vital organ to ensure longevity and quality of life. Understanding the changes your heart undergoes after 40 is the first step toward a proactive health strategy.The Impact of Aging on ArteriesAs we age, our blood vessels may begin to lose their elasticity, a process known as arterial stiffness. This can lead to higher blood pressure, which puts additional strain on the heart muscle. Furthermore, the buildup of plaque—a combination of fat, cholesterol, and other substances—can narrow the arteries, increasing the risk of coronary artery disease.Key Risk Factors to Monitor RegularlyTo keep your heart in peak condition, it is essential to keep a close eye on specific health markers. Regular screenings at a trusted facility like Suvira Hospital can help catch potential issues before they become emergencies.1. Blood Pressure (The Silent Killer)Hypertension often has no visible symptoms but is a leading cause of heart attacks and strokes. Maintaining a reading below 120/80 mmHg is ideal. If your numbers are consistently high, our specialists can help you manage them through diet, exercise, or medication.2. Cholesterol and Lipid ProfileNot all cholesterol is bad, but an imbalance between LDL (bad cholesterol) and HDL (good cholesterol) can lead to blockages. A comprehensive lipid profile test is recommended at least once a year after age 40.3. Blood Sugar and Diabetes RiskHigh blood sugar levels can damage blood vessels and the nerves that control your heart. Since type 2 diabetes often develops in middle age, monitoring your fasting blood glucose and HbA1c levels is vital.4. Body Mass Index (BMI) and Waist CircumferenceCarrying excess weight, particularly around the abdomen (visceral fat), is closely linked to heart disease. Aiming for a healthy BMI and a waist circumference that is less than half your height can significantly reduce cardiac strain.Lifestyle Changes for a Stronger HeartWhile genetics play a role, your daily habits are the most powerful tools you have for heart disease prevention. Implementing small, sustainable changes today can yield massive benefits in the years to come.Adopt a Heart-Healthy Diet: Focus on the Mediterranean style of eating. Incorporate plenty of leafy greens, whole grains, lean proteins, and healthy fats like olive oil and nuts. Reduce your intake of processed sugars and excessive salt.Prioritize Physical Activity: Aim for at least 150 minutes of moderate-intensity aerobic activity per week. This could include brisk walking, cycling, or swimming. Strength training twice a week also helps maintain metabolic health.Manage Stress Effectively: Chronic stress triggers the release of cortisol and adrenaline, which can increase heart rate and blood pressure. Practices like yoga, meditation, and ensuring 7-9 hours of quality sleep are essential for cardiac recovery.Quit Smoking and Limit Alcohol: Smoking is one of the most significant controllable risk factors for heart disease. Similarly, excessive alcohol consumption can lead to cardiomyopathy and arrhythmias.Recognizing Early Warning SignsHeart disease doesn't always announce itself with a dramatic chest pain. Sometimes, the signs are subtle and easily dismissed as signs of 'getting older.' Being aware of these symptoms can save your life.Unusual Fatigue: Feeling exhausted after simple tasks that used to be easy.Shortness of Breath: Difficulty breathing during mild exertion or while lying down.Persistent Cough: A cough that produces white or pink phlegm could be a sign of fluid buildup in the lungs due to heart issues.Swelling (Edema): Swelling in the ankles, feet, or legs.Dizziness or Lightheadedness: Feeling faint or unsteady without an obvious cause.Essential Cardiac Screenings at Suvira HospitalOur Cardiology Department in Jaipur is equipped with state-of-the-art diagnostic technology to provide a clear picture of your heart health. We recommend the following tests for individuals over 40:Electrocardiogram (ECG): To check the heart's electrical activity and rhythm.Treadmill Test (TMT): To observe how your heart responds to physical stress.Echocardiogram: An ultrasound of the heart to visualize its structure and pumping capacity.Calcium Scoring: A specialized CT scan to detect plaque buildup in the coronary arteries.When to See a CardiologistWhile annual checkups are recommended for everyone over 40, you should book an appointment with a cardiologist immediately if you have a family history of early heart disease, if you are starting a new vigorous exercise program, or if you experience any chest discomfort, palpitations, or unexplained fainting. Early intervention at Suvira Hospital can prevent minor issues from escalating into chronic conditions.ConclusionYour 40s are the perfect time to take charge of your cardiovascular health. By monitoring your vitals, adopting a nutritious diet, and staying active, you can significantly lower your risk of heart disease. At Suvira Hospital, Jaipur, our team of expert cardiologists is dedicated to providing compassionate, world-class care to help you live a long and healthy life.Don't wait for a warning sign. Book your comprehensive heart checkup with the Cardiology Department at Suvira Hospital today.Disclaimer: This article is for educational purposes only and is not a substitute for professional medical advice. Please consult a qualified cardiologist for diagnosis and treatment.Frequently Asked QuestionsHow often should I have a cardiac screening after 40?If you have no known risk factors, an annual checkup is generally recommended. However, if you have hypertension, diabetes, or a family history of heart disease, your cardiologist may suggest more frequent monitoring.What are the 'silent' symptoms of heart disease?Silent symptoms can include mild indigestion, jaw pain, unexplained neck or back pain, and extreme fatigue. Many people mistake these for general aging or stress, but they can indicate underlying heart issues.Can lifestyle changes alone prevent a heart attack?While lifestyle changes significantly reduce risk, they cannot eliminate it entirely, especially if genetics are involved. A combination of healthy habits and regular medical screenings is the most effective prevention strategy.
Read Article
Preventive health checkups are the cornerstone of modern medicine, allowing for the early detection of underlying conditions before they escalate into serious health issues. Suvira Hospital in Jaipur provides comprehensive screening packages designed to monitor vital organ functions and manage lifestyle-related risks through expert clinical evaluation.The Shift from Curative to Preventive HealthcareIn the past, medical intervention was primarily sought only when symptoms became unbearable. However, the modern healthcare landscape has shifted significantly toward preventive care. At Suvira Hospital Jaipur, we believe that 'prevention is better than cure' is not just a proverb but a clinical necessity. Preventive health checkups involve a series of medical tests and examinations intended to assess your current health status and identify potential risks for future illnesses.With the rising prevalence of lifestyle diseases such as diabetes, hypertension, and cardiovascular disorders, regular monitoring has become essential. Many of these conditions are 'silent killers,' meaning they often present no symptoms in their early stages. A comprehensive health screening can detect these issues early, making treatment more effective and often less invasive.Essential Components of a Comprehensive Health ScreeningA standard preventive health checkup at Suvira Hospital is meticulously designed to cover all major physiological systems. Depending on your age, gender, and medical history, our specialists recommend specific panels to ensure a thorough evaluation.Cardiovascular Health AssessmentHeart disease remains a leading cause of mortality worldwide. Our cardiac screening includes an Electrocardiogram (ECG) to check heart rhythm and a Lipid Profile to measure cholesterol levels. High levels of LDL (bad cholesterol) and triglycerides are significant risk factors for atherosclerosis and heart attacks. By identifying these levels early, our cardiologists can suggest lifestyle modifications or medications to safeguard your heart.Metabolic and Diabetic ScreeningDiabetes is a growing concern in Jaipur and across India. Our screening includes Fasting Blood Sugar (FBS) and HbA1c tests. While FBS provides a snapshot of your current glucose levels, the HbA1c test offers an average of your blood sugar over the past three months, providing a more accurate picture of your metabolic health. Early detection of pre-diabetes allows for interventions that can prevent the onset of Type 2 Diabetes.Liver and Kidney Function TestsThe liver and kidneys are vital for detoxification and metabolic balance. A Liver Function Test (LFT) checks for enzymes and proteins that indicate liver health, while a Kidney Function Test (KFT) measures urea and creatinine levels to ensure your kidneys are filtering waste effectively. Chronic kidney disease often goes unnoticed until it reaches an advanced stage, making these tests crucial for long-term health.Thyroid and Hormonal BalanceThyroid imbalances can lead to unexplained weight gain, fatigue, and mood swings. Our comprehensive packages include Thyroid Stimulating Hormone (TSH) tests to evaluate the health of your endocrine system. Hormonal balance is essential for maintaining energy levels and overall metabolic rate.Who Should Prioritize Regular Medical Checkups?While everyone can benefit from preventive care, certain groups are at a higher risk and should undergo screenings more frequently:Individuals over 35: As we age, the risk of metabolic and degenerative diseases increases.Those with a Family History: If conditions like cancer, heart disease, or diabetes run in your family, early screening is vital.High-Stress Professionals: Chronic stress can lead to hypertension and cardiac issues.Sedentary Lifestyles: Lack of physical activity increases the risk of obesity and related complications.Smokers and Alcohol Consumers: These habits significantly impact lung, liver, and cardiovascular health.Preparing for Your Visit to Suvira HospitalTo ensure the most accurate results from your health checkup, proper preparation is necessary. Most comprehensive blood tests require you to fast for at least 8 to 12 hours. During this time, you should only consume water. It is also advisable to avoid alcohol and heavy exercise 24 hours before your appointment.When you arrive at Suvira Hospital, our patient coordinators will guide you through the process. We recommend wearing comfortable clothing and bringing any previous medical records or a list of current medications. This information helps our doctors provide a more personalized consultation based on your health trajectory.Why Choose Suvira Hospital Jaipur?Suvira Hospital stands out as a premier healthcare provider in Jaipur due to our commitment to clinical excellence and patient-centric care. Our diagnostic wing is equipped with state-of-the-art technology, ensuring high precision in every test result. Furthermore, our multidisciplinary team of specialists is available to interpret your results and provide a clear roadmap for your health journey.We offer a range of customized health packages tailored to different age groups and health needs, from basic wellness screens to advanced executive checkups. Our goal is to provide a seamless experience where diagnostics, consultation, and follow-up care are all available under one roof.Conclusion: Take Charge of Your Health TodayYour health is your most valuable asset. Investing a few hours in a preventive health checkup can save you from years of medical complications and financial burden. At Suvira Hospital, we are dedicated to helping the people of Jaipur lead healthier, longer lives through proactive medical intervention.Don't wait for symptoms to appear. Schedule your comprehensive health checkup at Suvira Hospital today and take the first step toward a healthier tomorrow. Our expert team is here to support you with the best diagnostic and clinical care in the region.Frequently Asked QuestionsHow often should I get a full body checkup?For healthy adults under 40, a comprehensive checkup every 2-3 years is usually sufficient. However, for those over 40 or with existing health conditions, an annual checkup is highly recommended.Do I need to fast before my health screening?Yes, most comprehensive packages include blood sugar and lipid profile tests which require 8-12 hours of fasting for accurate results. You may drink plain water during this period.How long does the entire checkup process take?A standard preventive health checkup at Suvira Hospital typically takes 3 to 5 hours, depending on the complexity of the package and the number of consultations involved.
Read Article
Gallstones are a prevalent cause of acute abdominal pain, bloating, and severe digestive discomfort among adults. Left untreated, gallstone disease can lead to serious medical complications including cholecystitis, pancreatitis, and jaundice. At Suvira Hospital in Jaipur, state-of-the-art laparoscopic gallbladder surgery offers patients a minimally invasive, high-precision treatment with rapid recovery times.Understanding Gallbladder Disease and GallstonesThe gallbladder is a small, pear-shaped digestive organ situated beneath the liver on the upper right side of your abdomen. Its primary function is to store and concentrate bile—a digestive fluid produced by the liver that aids in breaking down dietary fats. However, imbalances in bile composition can lead to the crystallization of cholesterol or bilirubin, resulting in hard deposits known as gallstones (cholelithiasis).Gallstones vary in size from small grains of sand to large golf balls. While some individuals carry asymptomatic gallstones, many experience painful blockages when stones migrate into the cystic duct or common bile duct.Common Symptoms of Gallstone AttackSudden, Intense Abdominal Pain: Localized in the upper right quadrant or epigastric region, often radiating to the right shoulder or back.Nausea and Vomiting: Frequently triggered after consuming rich, fatty, or fried meals.Indigestion and Bloating: Chronic abdominal fullness, gas, and discomfort after eating.Jaundice: Yellowing of the skin and eyes, indicating a obstructed bile duct.Fever and Chills: Symptoms suggesting acute bacterial infection (acute cholecystitis).Why Laparoscopic Cholecystectomy is the Gold StandardWhen gallstones become symptomatic, surgical removal of the gallbladder—known as a cholecystectomy—is the definitive and safest treatment. Medications designed to dissolve gallstones are rarely effective and carry high recurrence rates once treatment stops. Fortunately, advances in minimal access surgery have made gallbladder removal safer and far less invasive than traditional open surgery.At Suvira Hospital in Jaipur, our surgical team utilizes keyhole laparoscopic technique. Rather than a large 5-to-7-inch abdominal incision, laparoscopic cholecystectomy requires only three or four tiny incisions ranging from 0.5 to 1 centimeter.Key Advantages of Laparoscopic SurgeryMinimal Pain & Scarring: Tiny incisions significantly lower post-operative pain and result in barely visible scars.Shorter Hospital Stay: Most patients are discharged within 24 to 48 hours following the procedure.Faster Return to Daily Routine: Normal non-strenuous activities can usually be resumed within 7 to 10 days.Reduced Risk of Infection: Minimally invasive procedures minimize tissue exposure, drastically cutting surgical site infection rates.Diagnostic Workup Before Surgery at Suvira HospitalAccurate diagnosis and meticulous pre-operative planning ensure maximum safety for every patient. When you visit the general surgery department at Suvira Hospital in Jaipur, our specialists perform a comprehensive clinical evaluation.Diagnostic Tests Include:Abdominal Ultrasound: The primary, highly accurate imaging modality used to detect gallstones, gallbladder wall thickening, and fluid accumulation.Liver Function Tests (LFTs): Blood tests to check bilirubin and enzyme levels, evaluating whether gallstones are obstructing the bile ducts.MRCP (Magnetic Resonance Cholangiopancreatography): Advanced non-invasive MRI imaging utilized if bile duct stones are suspected.Routine Blood & Cardiac Workup: Complete blood counts, kidney function tests, ECG, and chest X-rays to ensure complete fitness for general anesthesia.Step-by-Step: What Happens During Laparoscopic Gallbladder RemovalUnderstanding the procedure helps alleviate patient anxiety. Laparoscopic cholecystectomy is conducted under general anesthesia in our advanced, ultra-clean modular operating theaters.Step 1: Anesthesia & Port Creation: Once general anesthesia is administered, small 5-10 mm punctures are made in the abdomen.Step 2: Insufflation: Carbon dioxide gas is gently introduced to expand the abdominal cavity, creating a clear workspace for the surgical team.Step 3: High-Definition Visualization: A laparoscope—a slender tube equipped with a HD camera and light source—is inserted, projecting crystal-clear 3D images onto high-definition monitors.Step 4: Precision Dissection: Using specialized miniature instruments, the surgeon carefully isolates and clips the cystic duct and cystic artery, keeping nearby bile structures completely safe.Step 5: Extraction & Closure: The gallbladder is carefully removed inside a sterile endo-bag through one of the small incision ports. The incisions are then closed with dissolvable cosmetic sutures or surgical tape.Post-Operative Recovery Timeline & RehabilitationRecovery from laparoscopic gallbladder surgery is straightforward for the vast majority of patients. Following structured medical guidance ensures a rapid, uncomplicated return to peak health.In-Hospital Recovery (First 24 Hours)Patients are monitored in the recovery suite until the effects of anesthesia wear off. Gentle walking is encouraged within a few hours post-surgery to promote circulation and minimize gas discomfort. Oral fluids are introduced gradually, followed by light meals.At-Home Care & Dietary TransitionSince the human body continues to produce bile in the liver, digesting normal food remains entirely possible without a gallbladder. Bile now flows directly from the liver into the small intestine. However, a brief period of dietary adjustment is advisable:Days 1–5: Stick to low-fat, easily digestible, soft foods such as soups, porridge, boiled vegetables, and khichdi. Stay thoroughly hydrated.Weeks 2–3: Reintroduce normal high-fiber foods and lean proteins gradually. Avoid deep-fried, oily, or heavily spiced dishes during this transitional phase.Beyond 1 Month: Most patients digest a completely normal, healthy diet without any gastrointestinal side effects or restrictions.When to Consult a General Surgeon at Suvira HospitalIf you experience recurring upper right abdominal pain, indigestion after fatty meals, or have been diagnosed with gallstones via ultrasound, prompt expert evaluation is essential. Delaying treatment can lead to acute inflammation, infection, or dangerous bile duct obstructions that require emergency interventions.Suvira Hospital in Jaipur provides access to renowned general and laparoscopic surgeons, state-of-the-art diagnostic facilities, and compassionate post-operative care packages tailored to individual patient needs.Frequently Asked QuestionsCan a person live a normal life without a gallbladder?Yes, absolutely. The gallbladder only stores bile; it does not produce it. After surgery, your liver continues to produce bile, which flows directly into the small intestine to digest food normally without long-term health consequences.How many days of hospital stay are required for laparoscopic gallbladder surgery?Most patients stay at Suvira Hospital in Jaipur for 24 to 48 hours following laparoscopic cholecystectomy, depending on their individual recovery progress and general clinical condition.When can I return to work after laparoscopic gallbladder surgery?Most patients working sedentary or desk jobs can safely return to work within 7 to 10 days post-surgery. Strenuous physical labor or heavy lifting should be avoided for 3 to 4 weeks.
Read Article
Diagnostic testing is the foundation of effective preventive healthcare and accurate treatment planning. At Suvira Hospital in Jaipur, our General Healthcare department offers comprehensive clinical laboratory screenings, advanced imaging, and routine diagnostic testing to identify underlying health conditions before symptoms worsen. Understanding your health metrics empowers you and your care team to make informed medical decisions for long-term wellness.The Crucial Role of Diagnostic Testing in Preventive CareMedical diagnostic testing provides precise insights into the baseline functioning of your body's major organ systems. Routine lab work and diagnostic evaluations detect subtle biochemical changes, enabling early intervention for conditions like diabetes, dyslipidemia, liver disorders, and cardiovascular disease.Essential Categories of Diagnostic Tests Offered at Suvira Hospital1. Comprehensive Blood ProfilesBlood analyses offer a detailed overview of your metabolic and cellular health. Key tests include:Complete Blood Count (CBC): Evaluates red and white blood cells, hemoglobin, and platelets to detect anemia, infections, and immune health.Metabolic & Lipid Profiles: Measures blood glucose, cholesterol levels, triglycerides, and kidney/liver biomarkers to assess cardiometabolic risk.Thyroid Function Tests (T3, T4, TSH): Monitors endocrine function to manage fatigue, weight fluctuations, and metabolic balance.2. Diagnostic Imaging & Specialty EvaluationsComplementing clinical pathology, diagnostic imaging provides vital structural views of organs and tissues. From digital X-rays and ultrasonography to advanced electrocardiograms (ECG), imaging aids in identifying musculoskeletal injuries, visceral inflammation, and cardiac abnormalities early.Why Choose Suvira Hospital for Pathology and Testing in Jaipur?At Suvira Hospital, our clinical laboratory is driven by stringent quality control standards, ensuring maximum accuracy and swift turnaround times. Highlights of our diagnostic services include:Advanced automated diagnostic technology minimizing human errorExperienced board-certified pathologists, radiologists, and laboratory techniciansHassle-free sample collection with comfortable, patient-first care facilitiesIntegrated reporting sent directly to your consulting healthcare providerPreparing for Your Diagnostic AppointmentsTo ensure optimal test accuracy, certain diagnostic procedures require preparation. Fasting for 8 to 12 hours is typically required for lipid panels and fasting blood sugar tests. Always consult your physician at Suvira Hospital regarding medication schedules and specific pre-test instructions before your scheduled visit.
Read Article
When it comes to protecting health and finances, insurance has become one of the most important tools. In India, the medical expenses associated with hospitalization, surgery, or advanced treatment can be overwhelming. Many middle-class families find it difficult to manage the bills, while the upper-income groups demand more comprehensive and flexible insurance plans. This increasing demand for wider coverage has led to the rise of high-value health insurance in India. High-value health insurance refers to insurance policies that come with a significantly higher sum insured, often ranging from ₹50 lakhs to ₹1 crore or more. Such insurance caters to individuals, high-net-worth families, and those who want premium healthcare without worrying about financial limits. These plans not only provide higher coverage but also include additional insurance features like international treatment options, wellness programs, and complete protection against modern critical illnesses. This article covers every aspect of high-value health insurance in India, including its features, benefits, challenges, comparisons, and tips on how to select the right insurance plan. (adsbygoogle = window.adsbygoogle || []).push({}); Understanding High-Value Health Insurance High-value health insurance is a specialized category of health insurance aimed at people who need or desire enhanced coverage. Unlike standard health insurance plans that may cover ₹2 lakh to ₹10 lakh, high-value insurance policies extend the limit to crores. The primary purpose of this insurance is to provide financial security even in the worst-case scenarios such as: Advanced cancer treatments Organ transplants Major cardiac surgeries Long-term critical illness treatments Overseas medical care (adsbygoogle = window.adsbygoogle || []).push({}); For such situations, a regular insurance plan often falls short. That’s why high-value health insurance in India is considered an advanced form of protection. Why High-Value Health Insurance is Important in India India is witnessing rising healthcare inflation. Advanced medical treatments have become very costly in private hospitals. Let’s understand why these insurance plans are critical: Escalating medical costs Treatment for cancer, heart surgery, and organ transplant can easily cost more than ₹20–30 lakh. Without insurance, many families face debt or asset liquidation. Changing lifestyle patterns Urban lifestyles, high stress, poor diet, and lack of exercise have made Indians more prone to lifestyle-based critical illnesses. Insurance ensures financial preparedness. Preference for premium medical facilities High-income groups prefer private hospitals or international treatment. Insurance makes this affordable. Coverage against unforeseen situations Accidents, pandemics, or sudden serious diseases call for large insurance amounts. Peace of mind Knowing that insurance fully covers future medical needs removes stress and allows focus on recovery. Features of High-Value Health Insurance High-value health insurance plans in India come with exclusive features that make them attractive: High sum insured: ₹50 lakh, ₹1 crore, or even unlimited coverage. Coverage of advanced treatments: Cancer care, dialysis, robotic surgeries, cardiac procedures. Cashless hospitalization across a wide network of hospitals. International treatment coverage in selected insurance policies. Air ambulance and emergency evacuation benefits. Wellness benefits and annual health check-ups included. Day-care procedures coverage for modern surgeries. Pre- and post-hospitalization expenses covered for longer durations. Maternity, newborn, and vaccination cover in premium insurance. Optional riders like critical illness cover, accident disability riders, and top-ups. Types of High-Value Health Insurance Plans There are multiple formats of high-value insurance plans available in India: Individual High-Value Insurance Designed for single individuals requiring advanced coverage. It covers only one person under the insurance plan. Family Floater High-Value Insurance A single insurance policy with high coverage shared among family members, making it cost-efficient for high net-worth families. Top-Up and Super Top-Up High-Value Insurance These insurance plans enhance existing coverage by providing larger protection after the threshold limit is exhausted. Employer-Sponsored High-Value Insurance Organizations may provide high-value group insurance to top executives as part of corporate benefits. Who Should Buy High-Value Health Insurance in India? High-value health insurance plans are ideal for: (adsbygoogle = window.adsbygoogle || []).push({}); High-net-worth individuals (HNIs) wanting premium insurance protection. Families with a history of critical illness requiring advanced treatment. Frequent travelers who may need overseas treatment insurance support. Professionals and business owners who want uninterrupted financial stability. Individuals living in metro cities where treatment costs are higher. Older adults seeking maximum insurance coverage despite rising risks. Benefits of High-Value Health Insurance The advantages of high-value insurance are significant and wide-ranging: Comprehensive financial protection – Even crores of rupees in expenses are covered. Access to premium hospitals – Insurance lets you seek world-class care without financial worry. Global treatment options – Some plans allow international insurance claims. Family coverage – Entire household remains secured under one huge sum insured. Better lifestyle coverage – Insurance plans include wellness benefits and health rewards. Tax benefits – Premiums help reduce overall income tax liability. Peace of mind – Insurance eliminates uncertainty during emergencies. Limitations of High-Value Health Insurance Despite the premium protection, insurance plans also have some limitations: High premiums compared to regular insurance. Eligibility criteria may exclude those with pre-existing illnesses. Waiting period clauses apply, especially for maternity or pre-existing conditions. Limited awareness among the population about the advantages of such insurance. Complex policy terms may make it hard to understand coverage. How to Choose the Best High-Value Health Insurance in India Selecting the right insurance policy involves careful planning: Analyze coverage needs based on medical history and lifestyle. Compare multiple insurers for premiums and benefits. Look at sub-limits and co-pay clauses within the insurance plan. Check hospital network tie-ups to avail of cashless treatment. Review add-on riders like air ambulance, critical illness, or international cover. Read exclusions carefully before purchasing insurance. Check insurer’s claim settlement ratio for reliability. (adsbygoogle = window.adsbygoogle || []).push({}); Exclusions in High-Value Health Insurance Although comprehensive, there are exclusions that insurance applicants should be aware of: Illness within waiting period. Cosmetic or elective surgeries. Self-inflicted injuries or substance abuse. Experimental or unapproved treatments. Non-prescription alternative therapies. Understanding exclusions ensures realistic expectations of insurance benefits. High-Value Health Insurance vs Regular Insurance (adsbygoogle = window.adsbygoogle || []).push({}); Factor Regular Health Insurance High-Value Health Insurance Sum Insured ₹2 lakh – ₹10 lakh ₹50 lakh – ₹5 crore Coverage Limited Extensive, including foreign treatments Premiums Affordable Higher but value-packed Benefits Basic Premium features like wellness, air ambulance Target Audience General population HNIs, frequent travelers, premium seekers This table shows why insurance buyers looking for higher protection choose high-value plans. (adsbygoogle = window.adsbygoogle || []).push({}); Role of Insurance in Wealth Protection High-value insurance is not only about health but also wealth preservation. Without insurance, critical illness expenses can force families to sell property, spend retirement savings, or take huge loans. By investing in insurance with higher coverage, individuals ensure they can preserve wealth while securing health. Insurance thus becomes a vital financial planning tool for long-term stability. Technological Innovations in High-Value Health Insurance Modern insurance companies are adopting technology to enhance high-value plans: Digital policy issuance and claims. Telemedicine covered by insurance. Wearables and fitness apps linked with insurance discounts. AI-led claims settlement systems. Blockchain in insurance for data safety and transparent claims. These innovations make the insurance experience customer-friendly and efficient. Future of High-Value Health Insurance in India The future of high-value insurance in India looks strong due to: Increasing medical inflation requiring higher insurance coverage. Expansion of global treatment coverage in policies. Integration with wellness programs for proactive health management. Focus on mental health coverage within insurance. Customized high-value gold-class insurance plans for individuals. Case Studies of High-Value Insurance Usage Case 1: Critical Illness Treatment A senior executive diagnosed with cancer incurred treatment bills of ₹60 lakh. His high-value insurance plan provided complete coverage, saving the family from financial crisis. Case 2: Overseas Heart Surgery A businessman required heart surgery abroad. Insurance allowed air ambulance, international coverage, and hospital bill settlement seamlessly. Case 3: Multi-Member Family Coverage A family floater high-value insurance protected multiple members during the pandemic when several were hospitalized together, and coverage was large enough to handle all claims. Tips for Maximizing Benefits of High-Value Insurance (adsbygoogle = window.adsbygoogle || []).push({}); Buy insurance early for lower premiums. Regularly review health needs and adjust coverage. Combine life insurance with health insurance for full safety. Use preventive care offers from insurance providers. Renew policies without break to avoid waiting periods again. Consider super top-up insurance plans. Educate dependents on claim processes. High-Value Insurance and Tax Benefits in India Premiums for high-value insurance plans are eligible for deductions under Section 80D of the Income Tax Act. Tax benefits differ depending on: Coverage for individuals, families, or senior citizens. The amount of insurance premium paid. Additional coverage riders. Thus, insurance not only secures health but also reduces tax liability. (adsbygoogle = window.adsbygoogle || []).push({}); Conclusion High-value health insurance in India is not just a luxury—it is fast becoming a necessity in an era of rising medical inflation, increasing critical illnesses, and global health risks. By offering large coverage amounts, premium facilities, and international benefits, this insurance creates a strong safety net for individuals and families. Choosing the right high-value insurance requires awareness of needs, comparison of plans, and a close evaluation of insurer credibility. Once secured, such insurance acts as both a financial shield and a peace-of-mind guarantee. For Indians who believe in future-ready health planning, high-value health insurance is the smartest investment for protecting both health and wealth.
Read Article
Life is full of uncertainties, and health challenges can come without warning. While basic health insurance protects against hospitalization and routine treatments, it often falls short when it comes to critical illnesses like cancer, heart attack, stroke, kidney failure, or organ transplants. These serious medical conditions not only involve high treatment costs but can also lead to loss of income due to long recovery periods. This is where critical illness insurance plays a vital role. Critical illness insurance provides a lump sum payout upon diagnosis of a covered illness, ensuring financial stability during one of the toughest phases of life. Unlike regular health coverage, this special insurance plan is designed to meet massive treatment costs, ongoing medical expenses, and daily living costs during recovery. In this comprehensive article, we will cover everything you need to know about critical illness insurance: its features, benefits, limitations, best practices, industry trends, and how it fits into your personal financial planning. (adsbygoogle = window.adsbygoogle || []).push({}); What Is Critical Illness Insurance? Critical illness insurance is a specialized form of health insurance that pays a predetermined lump sum amount when the insured is diagnosed with a serious illness listed in the policy. Conditions such as cancer, heart disease, paralysis, organ failure, and major surgeries are common inclusions. Unlike traditional health insurance, which pays hospital bills and medical expenses, this type of insurance provides money directly to the policyholder. The payout can be used for: Medical treatment and hospitalization costs Post-treatment rehabilitation and therapies Household expenses during recovery Loan repayments and education fees of dependents Hiring caregivers or support services In essence, critical illness insurance provides financial freedom to focus on recovery instead of stressing about bills. Importance of Critical Illness Insurance The growing demand for critical illness insurance is driven by several factors: Rising medical inflation – The cost of treatments such as chemotherapy, organ transplant, and cardiac surgeries is extremely high. Insurance helps manage these unavoidable costs. Increasing lifestyle-based diseases – Sedentary lifestyles, stress, unhealthy diets, and pollution have made people prone to critical illnesses. Insurance is necessary for financial preparedness. Long recovery period – Unlike minor illnesses, critical diseases often require prolonged rest, which means loss of income. Insurance ensures stability even when earnings are disrupted. Limited coverage under basic health insurance – Standard insurance policies may not cover the entire cost of critical illness treatments or post-care needs. Peace of mind – Insurance provides psychological assurance that financial aid will be available when needed. Key Features of Critical Illness Insurance Plans Critical illness insurance has unique features that make it distinct from other insurance options: Lump sum payment on diagnosis of covered illness. Wide range of illnesses covered, sometimes more than 30 conditions. Survival period clause, typically requiring the insured to survive 30 days after diagnosis to claim insurance benefits. Affordable premiums compared to the sum assured because coverage is specific. Fixed benefit structure irrespective of actual medical bill amounts. Flexibility of funds – payout money can be used for any purpose, not just medical bills. Tax benefits on premiums under prevailing tax laws. Riders available to add critical illness coverage to existing insurance. (adsbygoogle = window.adsbygoogle || []).push({}); Types of Critical Illness Insurance Critical illness insurance is offered in various formats to suit different needs: Standalone Critical Illness Insurance This is a separate insurance policy solely covering major illnesses. It offers substantial payouts and wide coverage. Rider/Add-on to Health Insurance Critical illness coverage can be added to an existing health insurance policy for extra protection. This option is often cheaper. Rider/Add-on to Life Insurance Life insurance policies can include critical illness riders, ensuring payout even during lifetime if diagnosed with a serious disease. Group Critical Illness Insurance Employers sometimes offer group critical illness coverage as part of employee benefits, but coverage is usually limited. Illnesses Covered by Critical Illness Insurance While the number of illnesses covered varies by insurance provider, some commonly included conditions are: Cancer of specified severity Heart attack (first occurrence) Stroke resulting in permanent symptoms Kidney failure requiring dialysis Major organ transplant (liver, lung, pancreas, kidney, heart) Bypass surgery (coronary artery) Multiple sclerosis Paralysis of limbs Permanent loss of vision or hearing Alzheimer’s and Parkinson’s disease (in advanced stage) This extensive list ensures that policyholders are covered for costly and life-threatening health conditions. Benefits of Critical Illness Insurance Critical illness insurance brings holistic advantages to both financial planning and health security: Financial protection – Large payouts cover astronomical healthcare expenses. Income support – Insurance ensures household expenses, rents, EMIs, and bills are manageable during treatment. Treatment flexibility – Insurance payout allows choice of advanced treatments, even abroad. Debt protection – Prevents families from selling assets or borrowing to pay medical costs. Complete freedom of use – Unlike health insurance, funds can be used for lifestyle, recovery, or household needs. Tax advantage – Premiums offer tax-saving benefits. Mental relief – Insurance reduces anxiety about the financial impact of illness. Exclusions in Critical Illness Insurance Critical illness insurance, like all insurance products, has certain exclusions: Pre-existing diseases diagnosed before buying insurance Illnesses contracted within initial waiting period of 90 days Conditions not listed in the policy schedule Death within the survival period (usually 30 days post-diagnosis) Minor or early-stage illnesses Self-inflicted injuries or substance abuse-related conditions (adsbygoogle = window.adsbygoogle || []).push({}); Challenges in the Critical Illness Insurance Market The adoption of critical illness insurance faces challenges, such as: Awareness gap: Many people confuse it with normal health insurance. High premium for older applicants: Insurance premiums increase with age. Limited policy coverage: Not all illnesses or early stages are covered. Complicated claim process: Misunderstanding terms can lead to disputes. Dependency on employer’s group insurance: People fail to buy personal coverage outside work. How to Choose the Right Critical Illness Insurance Selecting the right insurance plan requires careful thought: Check illnesses covered – More extensive coverage is better. Compare sum assured – Ensure coverage is high enough to meet actual costs. Look at survival period clause – Shorter survival periods are beneficial. Read exclusions and limitations in the insurance document carefully. Premium affordability – Strike a balance between coverage and budget. Insurer’s claim settlement ratio – Indicator of reliability of the company. Network support and reputation – Choose insurers with strong customer service. Role of Insurance in Financial Planning Insurance, especially critical illness insurance, plays a crucial role in overall financial planning: Complements life and health insurance by covering high-risk events. Protects long-term savings and investments from being depleted. Ensures uninterrupted financial stability for family members. Complements retirement planning, especially in old age when risks increase. Helps in wealth preservation by avoiding emergency asset liquidation. When integrated with other insurances such as life insurance, motor insurance, and standard health insurance, critical illness insurance creates a comprehensive protection net. Technological Innovations in Critical Illness Insurance Digital disruption has transformed the insurance industry, making critical illness coverage more user-friendly: AI and automation in claim processing reduce delays. Wearables integrated with insurance apps offer discounts for healthy lifestyles. Telemedicine coverage enables consultations remotely. Online comparison portals make finding the right insurance easier. Blockchain in insurance contracts improves transparency and claim authentication. Future of Critical Illness Insurance Plans The future of this insurance segment looks promising. Trends include: More customized insurance solutions tailored to individuals. Expanding global coverage to support medical tourism. Inclusion of mental health conditions in insurance policies. Lower premiums due to AI-driven risk prediction. Integration with preventive healthcare apps to reward healthy living. Case Scenarios: Impact of Critical Illness Insurance Example 1 – Cancer Treatment A person diagnosed with cancer may face expenses of several lakhs for chemotherapy and surgery. With critical illness insurance, they receive lump sum funds to cover treatment without draining savings. Example 2 – Stroke Recovery After a stroke, treatment, rehabilitation, and long-term care might prevent the insured from working for months. Insurance payout covers essential expenses, loans, and therapy. Example 3 – Organ Transplant Transplants involve massive costs along with travel and post-surgery care. Only strong insurance coverage can provide the necessary funds. Tips for Maximizing Critical Illness Insurance Benefits (adsbygoogle = window.adsbygoogle || []).push({}); Buy insurance early to enjoy lower premiums. Combine basic health insurance with critical illness riders. Opt for higher sum assured to account for inflation. Disclose complete medical history to avoid claim rejection. Review your insurance coverage every 3–5 years. Consider taking global coverage if traveling regularly. Educate family about claim process in case the insured is incapacitated. Difference Between Health Insurance and Critical Illness Insurance Aspect Health Insurance Critical Illness Insurance Coverage Hospitalization, surgery, pre/post hospital bills Lump sum on diagnosis of listed illness Benefit Payment Actual medical bills reimbursed or cashless Fixed sum regardless of actual expenses Illness Scope Covers standard treatments Only critical illnesses (limited list) Usage of Funds Strictly medical Free usage, medical or non-medical Premiums Based on wide coverage Generally lower, based on selected diseases Both types of insurance complement each other rather than replace one another. (adsbygoogle = window.adsbygoogle || []).push({}); Conclusion Critical illness insurance has emerged as a critical tool for financial security in today’s health landscape. It fills the gaps left by traditional insurance policies by offering lump sum payouts that can be used flexibly for any need—be it treatment, household expenses, or debt payments. With rising medical costs, lifestyle-related health risks, and unpredictable healthcare needs, investing in critical illness insurance is a wise decision. It ensures you and your family have sustained financial support, peace of mind, and holistic protection. In the end, insurance is not just about covering expenses—it is about preparing for life’s toughest challenges while securing your loved ones’ future.
Read Article
Health is one of the most valuable assets in life, and protecting it should be a priority. With the rising cost of medical services globally, relying only on savings is no longer practical. Health insurance plays a vital role here, ensuring that individuals and families can access quality healthcare while protecting their financial stability. Medical emergencies can strike at any time, and the expenses for hospitalization, surgery, or treatment can drain years of savings. Insurance ensures that such financial burdens do not derail your life goals. In this comprehensive article, we will cover everything about health insurance, its importance, features, benefits, challenges, and how to select the right policy from the available insurance plans. (adsbygoogle = window.adsbygoogle || []).push({}); What Is Health Insurance? Health insurance is a form of insurance policy that provides financial coverage for medical expenses. Under this arrangement, the insured pays a fixed premium, and in return, the insurance company agrees to cover expenses arising from healthcare needs. The scope of coverage depends on the chosen plan and insurer. This form of medical insurance acts as a financial buffer against uncertainties such as accidents, critical illnesses, or emergency treatments. Without insurance, individuals often struggle to pay for unexpected healthcare bills. Therefore, insurance serves both as a safety net and a smart financial planning tool. Importance of Health Insurance The role of health insurance in today’s world is critical. Here are a few reasons why insurance coverage is essential: Rising medical costs: Without medical insurance, expenses for hospitalization and surgeries can wipe out savings. Lifestyle diseases: Conditions such as diabetes, hypertension, and obesity require long-term medications, which insurance can cover. Uncertainty of emergencies: Accidents or critical illnesses can happen anytime, and insurance ensures financial protection. Preventive care: Some insurance companies provide free check-ups, vaccinations, and wellness incentives. Peace of mind: With insurance, you are assured that medical treatment won’t cause financial hardship. (adsbygoogle = window.adsbygoogle || []).push({}); Features of Health Insurance Policies Health insurance policies have evolved to meet diverse needs. Common insurance features include: Hospitalization coverage: Includes doctor’s fees, nursing charges, room rent, and ICU facilities. Day-care treatment: Insurance covers advanced procedures that do not require 24-hour admission. Cashless treatment system: At network hospitals, the insurance company pays directly. Pre- and post-hospitalization coverage: Expenses before and after treatment are included. Coverage for family members: Through family floater insurance plans, all members are secured. Riders and add-ons: Insurance add-ons like maternity cover, accident cover, and critical illness cover expand protection. Types of Health Insurance Health insurance is not one-size-fits-all. There are multiple types of insurance plans depending on individual and family needs: Individual Health Insurance Covers a single person under the insurance policy. Each person needs their own policy if not opting for family floater insurance. Family Floater Health Insurance One policy covers multiple family members. Insurance coverage is shared among them, offering cost-effective protection. Group Health Insurance Employers commonly provide this insurance benefit to employees. It remains valid only during employment with the organization. Critical Illness Insurance Provides a lump sum amount if diagnosed with a critical illness listed in the insurance agreement. Senior Citizen Health Insurance Specially designed for older adults, this insurance plan accounts for higher risks and medical needs. Maternity Health Insurance Takes care of expenses related to pregnancy, delivery, and newborn care. Top-Up Insurance Plans Enhances the sum insured of your existing insurance policy once the base coverage is exhausted. Benefits of Health Insurance Choosing good health insurance delivers several benefits beyond financial support: Financial protection: Insurance saves policyholders from draining their savings. Wide hospital network: Insurance companies have tie-ups for easy cashless treatment. Tax benefits: Premiums paid for insurance are often tax deductible. No-claim bonus: Insurance rewards policyholders who have not made claims during the previous year. Preventive healthcare: Insurance promotes early diagnosis through free check-ups. Mental peace: Insurance ensures stress-free treatment during emergencies. Exclusions in Health Insurance Insurance coverage is broad, but not unlimited. Policies often list exclusions such as: Pre-existing diseases before waiting period expires. Cosmetic or aesthetic surgeries not prescribed medically. Dental or vision care without extra insurance coverage. Injuries due to self-harm or drug abuse. Expensive alternative therapies outside prescribed insurance terms. (adsbygoogle = window.adsbygoogle || []).push({}); Challenges in the Insurance Industry Even though insurance adoption is increasing, the industry faces hurdles: Lack of insurance awareness in rural and semi-urban areas. Inadequate insurance coverage amounts for rising treatment costs. Claim rejections due to incomplete understanding of policy terms. Expensive premiums for older customers buying new insurance. Dependence on employer’s group insurance without having personal policies. Choosing the Right Insurance Plan Selecting suitable insurance requires careful analysis: Check the total insurance coverage amount needed. Compare premiums versus benefits in insurance policy documents. Ensure your insurer has a wide hospital network. Review inclusions, exclusions, and waiting periods in insurance policies. Select insurance add-ons like critical illness cover or maternity cover for flexibility. Research the claim settlement ratio and reputation of the insurance provider. Preventive Healthcare and Insurance Health insurance is no longer limited to emergencies. Many insurance providers now promote preventive care. Insurance covers annual health examinations, vaccinations, wellness activities, and fitness tracking apps. Reward points in certain insurance schemes motivate people to maintain better lifestyles, directly reducing hospitalizations. Digital Insurance and Technology The rise of digital platforms has transformed the insurance industry: Digital policies eliminate paperwork and can be accessed anytime. Telemedicine insurance coverage lets customers consult doctors online. AI-driven claim settlements simplify and speed up reimbursement. Wearable devices linked to insurance apps reward healthy activity. This increased technology adoption makes insurance policies easier to use and more customer-friendly. Insurance in Financial Planning Insurance is not just about health; it is a pillar of financial security. Along with savings, retirement planning, and investments, insurance ensures stability. Without medical insurance, unexpected health crises can force families to liquidate assets or borrow money. A comprehensive insurance portfolio balances personal finance by minimizing risks. Future of Health Insurance The global insurance industry is rapidly evolving: A shift from traditional insurance plans to more customized insurance solutions. Insurance policies that include mental health treatments. Wider global insurance coverage as medical tourism grows. Stronger ties between insurance and digital e-health records. Value-linked insurance models based on health outcomes. These trends point to a more customer-focused and digital-first insurance market. Conclusion Health insurance is an essential safeguard against medical uncertainties. With healthcare expenses rising worldwide, relying only on savings is risky. Insurance policies provide not just financial protection but also better healthcare access, preventive care, and peace of mind. Choosing the right insurance requires understanding personal health needs, evaluating insurer reliability, and ensuring adequate coverage. A well-chosen insurance plan protects both your health and wealth, ensuring a more secure future. In the end, insurance is not just a product—it is a promise of financial safety, healthy living, and long-term protection.
Read Article
Select Your Post and Continue to Fill Application Form Click on your Relevent Field to Continue Fill Form 1. Nursing Staff : Fresher & Experinced (180 Post ) 2. Receptionist (Male & Female): (26 Post ) 3. IT Executive (2 Post ) 4. Junior Resident (6 Post ) 6. Multi Task Staff (30 Post ) 7. General Duty Staff (36 Post ) 8. Billing Department Vacancy (10 Post ) Click on your Relevent Field to Continue Fill Form
Read Article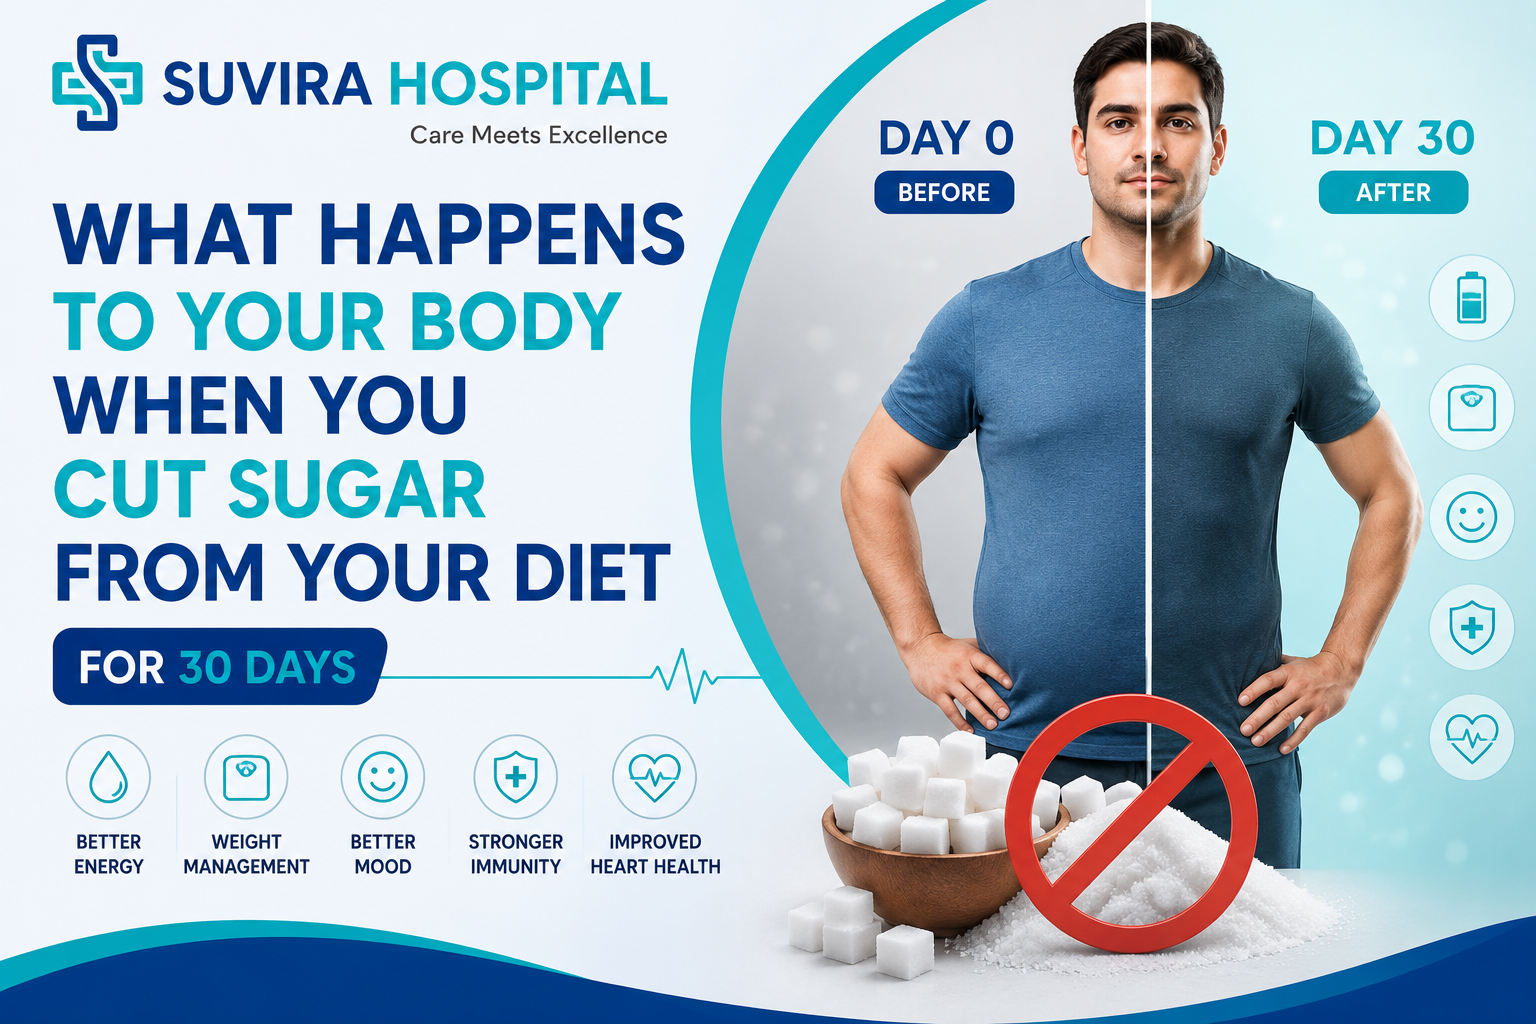
Cutting sugar from your diet for 30 days triggers a powerful transformation across both body and mind. The results can feel dramatic, ranging from initial cravings and irritability to improved energy, clearer skin, weight loss, and better mental clarity. Here’s an in-depth guide on what happens when you cut sugar for 30 days and the science behind each stage of your body’s reset. (adsbygoogle = window.adsbygoogle || []).push({}); (adsbygoogle = window.adsbygoogle || []).push({}); (adsbygoogle = window.adsbygoogle || []).push({}); The Initial Phase: Sugar Withdrawal (Days 1–7) Removing sugar from your daily food and drink can be surprisingly challenging in the first week. This is mainly because sugar activates the brain’s reward system, causing real cravings. Common early symptoms include irritability, mood swings, tiredness, headaches, and strong urges for sweet foods. Your brain, having relied on sugar for dopamine surges, temporarily registers the change as loss, which can lead to feelings of mild anxiety or fatigue. If you consumed large quantities of sugar prior, withdrawal can also bring symptoms like foggy thinking and restlessness. (adsbygoogle = window.adsbygoogle || []).push({}); (adsbygoogle = window.adsbygoogle || []).push({}); (adsbygoogle = window.adsbygoogle || []).push({}); The good news: these initial symptoms usually fade as your body’s insulin and blood sugar levels begin to stabilize. Week Two: Energy and Blood Sugar Stabilization As you transition into week two without added sugar, the body starts showing deeper signs of balance. Blood sugar levels become more stable. With sugar spikes and crashes gone, you may notice fewer bouts of low energy and a general improvement in mood. Energy slumps disappear. Many people report no longer experiencing the afternoon “crash” that follows a high-sugar lunch or snack. Food cravings reduce significantly, making it easier to stick to more nourishing, whole foods. Some people already notice improvements in digestion and a reduction in bloating. (adsbygoogle = window.adsbygoogle || []).push({}); (adsbygoogle = window.adsbygoogle || []).push({}); (adsbygoogle = window.adsbygoogle || []).push({}); With insulin levels returning to normal, the body also becomes better at burning stored fat for energy, potentially resulting in the first signs of weight loss. Week Three: Visible Physical Changes Around days 15–21, the most visible external changes often begin. Skin may clear up and improve. Sugar drives inflammation and contributes to acne and dullness; cutting it out produces a more radiant complexion and fewer breakouts. Weight loss becomes noticeable. Consuming fewer calories from sugary foods and drinks, and experiencing better fat metabolism, many notice their clothes begin to fit better. Reduced water retention and bloating. Sugar causes your body to retain water; without it, your body feels less puffy and more defined. Stable, sustained energy is now more reliable through your entire day. Week Four: Long-term Benefits Set In By days 22–30, profound internal and external changes are much more established. Cravings for sugar are dramatically reduced. Many find that foods and drinks they once loved now taste overwhelmingly sweet, making it easy to avoid them. Mental clarity and focus improve. Less sugar means fewer mental highs and lows; people often feel more alert, less foggy, and mentally sharper. Appetite control and portion sizes stabilize. Without constant hunger triggered by blood sugar swings, it’s easier to eat mindfully. Digestive health improves. The gut benefits from less sugar-fed bad bacteria, reducing gas and discomfort while promoting nutrient absorption. Better sleep patterns emerge. Many report falling asleep more easily and benefiting from deeper, restorative rest. (adsbygoogle = window.adsbygoogle || []).push({}); (adsbygoogle = window.adsbygoogle || []).push({}); (adsbygoogle = window.adsbygoogle || []).push({}); Clinically Proven Health Improvements 1. Weight Management Most people experience some weight loss (often 3–7 pounds or more), especially around the waist, as the body taps into stored fat, and overall calorie intake decreases. 2. Clearer, Glowing Skin Sugar accelerates aging and inflammation through glycation—a process that damages collagen. Removing sugar often means fewer breakouts, reduced puffiness, and a healthier glow. 3. Enhanced Liver and Kidney Health The liver, which is taxed heavily by excess sugar (especially fructose), begins to heal. Fatty liver changes can start reversing, and kidney efficiency improves as sugar stress eases. (adsbygoogle = window.adsbygoogle || []).push({}); (adsbygoogle = window.adsbygoogle || []).push({}); (adsbygoogle = window.adsbygoogle || []).push({}); 4. Stronger Immune System Sugar suppresses immune response by weakening white blood cells. After 30 days, you may notice fewer colds and better resilience against infection. 5. Cardiovascular Health Blood pressure, cholesterol, and inflammation markers begin to improve, reducing long-term risk for heart disease. (adsbygoogle = window.adsbygoogle || []).push({}); (adsbygoogle = window.adsbygoogle || []).push({}); (adsbygoogle = window.adsbygoogle || []).push({}); 6. Improved Mental Health Mood swings, anxiety, and irritability tied to sugar highs and lows decline. Clearer thinking, better memory, and increased mental energy are common benefits. 7. Better Dental Health Less sugar exposure means fresh breath, reduced plaque, decreased tooth sensitivity, and lower risk of cavities or gum inflammation. (adsbygoogle = window.adsbygoogle || []).push({}); (adsbygoogle = window.adsbygoogle || []).push({}); (adsbygoogle = window.adsbygoogle || []).push({}); Tips for Succeeding with a 30-Day No Sugar Challenge Stock up on whole foods: Focus on vegetables, fruits with low glycemic index, whole grains, lean proteins, healthy fats, and nuts. Read labels: Even “healthy” processed foods often include hidden sugars in forms like syrup, glucose, maltose, or honey. Replace sugary drinks: Hydrate with water, herbal teas, or infused waters. Expect emotional ups and downs: Stay aware of cravings and moods—they are temporary and fade quickly. Celebrate victories: Remind yourself how your body feels at each positive milestone. What Happens After 30 Days? Once you complete 30 days sugar-free, your relationship with sugar usually changes permanently. Most people report little desire to return to their old habits, enjoying a new sense of wellbeing and control over cravings. Your palate becomes more sensitive, appreciating natural sweetness in foods you once found bland. If you choose to reintroduce sugar, you’ll do so more consciously and in moderation. Conclusion Eliminating added sugar from your diet for 30 days unlocks transformative changes. The journey isn’t always comfortable at first, but the benefits—a healthier body, sharper mind, glowing skin, a more stable mood, and dramatically improved energy—make it one of the most rewarding health challenges you can undertake. By committing to this challenge, you pave the way for a healthier, more energized, and more vibrant future.
Read Article
The ideal sum insured in health insurance is the coverage amount that provides comprehensive protection against unforeseen medical expenses, ensuring that individuals and families do not face financial hardship during medical emergencies. Here’s a detailed, expert-driven guide to understanding and choosing the ideal sum insured for health insurance in India. (adsbygoogle = window.adsbygoogle || []).push({}); (adsbygoogle = window.adsbygoogle || []).push({}); (adsbygoogle = window.adsbygoogle || []).push({}); What Is Sum Insured in Health Insurance? Sum insured is the maximum amount your health insurer will pay towards your medical expenses in one policy year. Coverage exceeding this limit must be borne out of pocket. Selecting an adequate sum insured is crucial, as it directly determines financial safety during medical emergencies. Why Selecting the Right Sum Insured Matters Medical costs in India are rising due to inflation and advancements in treatment. An inadequate sum insured can result in significant out-of-pocket expenses, nullifying the purpose of health insurance. Over-insuring can strain your finances due to higher premiums, making it important to find a careful balance. Factors Affecting the Ideal Sum Insured Age and Life Stage Young adults (20s–30s) often need moderate coverage, typically ₹3–5 lakh. Middle-aged adults or families should opt for higher coverage, usually ₹10–15 lakh or more. (adsbygoogle = window.adsbygoogle || []).push({}); (adsbygoogle = window.adsbygoogle || []).push({}); (adsbygoogle = window.adsbygoogle || []).push({}); Family Structure Individual plans may require a lower sum insured than family floaters. For families with children and senior members, a minimum cover of ₹15 lakh is recommended. More members increase risk, so the sum insured should scale with family size. Income and Affordability The premium should generally not exceed 2% of annual income. Calculate the sum insured based on your financial ability to pay premiums without straining your household budget. Healthcare Costs in Your City Medical expenses are much higher in metro cities than in Tier 2 or Tier 3 towns. Metro residents should consider a base of ₹10 lakh, adjusting for premium and healthcare cost variations. Medical History and Lifestyle A family or personal history of illnesses (like heart disease, cancer, diabetes) calls for increased coverage. Unhealthy lifestyles or pre-existing conditions require a higher sum insured for adequate financial protection. Medical Inflation Medical costs in India are increasing by 10–15% annually. It’s essential to factor in future cost escalation when selecting your sum insured, not just current costs. How to Calculate Your Ideal Sum Insured Assess the total healthcare costs in your area. Gather details about major hospitalization expenses in your city. Account for multiple claims. Ensure that your sum insured can cover more than one major hospitalization in the same year. Include top-up plans. If a higher base sum insured seems unaffordable, combine an affordable base plan with a top-up or super top-up for increased protection. Aim for 10–15 times your monthly salary. This simple rule of thumb helps most urban families stay insulated from major healthcare costs. (adsbygoogle = window.adsbygoogle || []).push({}); (adsbygoogle = window.adsbygoogle || []).push({}); (adsbygoogle = window.adsbygoogle || []).push({}); Expert Recommendations for 2025 Demographic Suggested Minimum Sum Insured Rationale Young Single (20s) ₹3–5 lakh Lower medical risk Couple (no kids) ₹5–10 lakh Moderate coverage Nuclear Family (2+2) ₹10–15 lakh Covers rising family expenses With Senior Citizen Parents ₹15–25 lakh Higher risk and cost of care Metro Residents ₹10 lakh minimum Urban medical expenses High-Risk Medical History ₹15–25 lakh Recurring/chronic illnesses Mistakes to Avoid Underestimating future medical needs or ignoring inflation. Selecting low coverage for the sake of saving on premiums. Not revisiting the sum insured as your life stage/financial situation evolves. Failing to update your policy when your family size or dependents increase. Advanced Tips Opt for plans with a no-claim bonus (NCB). This increases your coverage in claim-free years. Check for sublimits and co-payments which reduce actual coverage on specific illnesses or procedures. Prefer policies with restore benefits, where the sum insured is automatically refilled if exhausted after a claim. Choose cashless network hospitals to avoid upfront payments during emergencies. (adsbygoogle = window.adsbygoogle || []).push({}); (adsbygoogle = window.adsbygoogle || []).push({}); (adsbygoogle = window.adsbygoogle || []).push({}); Using Top-Up and Super Top-Up Plans A base policy of ₹5–10 lakh combined with a super top-up up to ₹20–25 lakh gives robust protection without excessive premium hikes. Super top-ups kick in after your base sum insured is exhausted, offering high protection for a marginally higher cost. Recommendations for Reviewing Your Policy Reassess your sum insured every year or after major life events such as marriage, childbirth, relocation, or upon diagnosis of a critical illness. As medical inflation tends to outpace general inflation, consider upgrading your coverage periodically. Popular Health Insurance Plans and Their Sum Insured Options (2025) (adsbygoogle = window.adsbygoogle || []).push({}); (adsbygoogle = window.adsbygoogle || []).push({}); (adsbygoogle = window.adsbygoogle || []).push({}); Insurer Plan Name Sum Insured Options Notes Star Health Family Health Optima ₹3–25 lakh Good daycare & network coverage HDFC ERGO Optima Restore ₹5–50 lakh Automatic restoration benefit Max Bupa (Niva Bupa) Health Companion ₹5–100 lakh+ No room rent limits ICICI Lombard Complete Health ₹3–50 lakh Lifelong renewal, wellness offers Apollo Munich (HDFC) Easy Health Family ₹3–20 lakh Includes maternity Religare (Care Health) Care Plan ₹5 lakh–6 crore Worldwide coverage options Tata AIG MediCare Premier ₹3–30 lakh Option for global cover Bajaj Allianz Family Floater ₹5–50 lakh Widely accepted in hospitals New India Assurance Family Mediclaim ₹2–15 lakh Government reliability Conclusion Choosing the right sum insured is about balancing your health needs, local medical costs, family structure, and future risks. Most urban, middle-class families should start with at least ₹10 lakh coverage, adjusting upward for age, medical history, or inclusion of senior citizens. Combining a well-structured base policy with super top-up plans provides optimal protection against India’s fast-rising medical inflation. Always review your policy annually and increase coverage in step with your evolving lifestyle and healthcare trends.
Read Article
HMPV Overview Human metapneumovirus (HMPV), a pathogen that, while not new, has gained attention recently in the global health arena. This comprehensive guide aims to shed light on HMPV, its impact, and what we can do to protect ourselves and our communities. What is HMPV Virus (Human Metapneumovirus)? (adsbygoogle = window.adsbygoogle || []).push({}); .php (adsbygoogle = window.adsbygoogle || []).push({}); (adsbygoogle = window.adsbygoogle || []).push({}); (adsbygoogle = window.adsbygoogle || []).push({}); (adsbygoogle = window.adsbygoogle || []).push({}); Human metapneumovirus or HMPV is a respiratory virus that was first identified in 2001 by Dutch researchers. Despite its relatively recent discovery, the virus has likely been circulating in human populations for decades. HMPV belongs to the Pneumoviridae family, which includes other respiratory pathogens like respiratory syncytial virus (RSV). Primarily, the virus affects the respiratory system, causing infections that range from mild cold-like symptoms to severe respiratory distress. While it can infect individuals of all ages, HMPV poses a particular threat to young children and older adults, including those with compromised immune systems. Characteristics of Human Metapneumovirus (hMPV) Human metapneumovirus (hMPV) is a significant respiratory pathogen with the following key characteristics: Virus Family: hMPV belongs to the Pneumoviridae family, sharing similarities with respiratory syncytial virus (RSV). Structure: It is an enveloped, single-stranded RNA virus. Transmission: Spreads through respiratory droplets, direct contact with infected individuals, or contaminated surfaces. Symptoms: Causes a spectrum of respiratory illnesses, from mild cold-like symptoms to severe conditions like bronchiolitis, pneumonia, and asthma exacerbations. Seasonality: Typically more prevalent in late winter and early spring, with outbreaks resembling seasonal patterns of other respiratory viruses. Target Groups: Primarily affects young children, older adults, and individuals with weakened immune systems or chronic respiratory conditions. Diagnosis: Laboratory tests such as PCR, antigen detection, or viral culture are used for accurate identification. Treatment: No specific antiviral exists; treatment is focused on symptom management and supportive care. Prevention: Good hygiene practices and avoiding close contact with infected individuals are essential for reducing the spread. These characteristics make hMPV a notable virus, especially among high-risk populations. HMPV Transmission: How It Spreads and Who’s at Risk HMPV spreads through close contact with infected individuals, primarily via respiratory droplets or aerosols released during coughing or sneezing. The virus can survive on surfaces for short periods, making hand hygiene crucial in preventing transmission. The incubation period for HMPV is estimated to be between three to six days, during which an infected person may be contagious without showing symptoms. This characteristic makes containment challenging and emphasizes the importance of preventive measures. HMPV infections have been noted to have a higher impact on children under the age of 14, sometimes straining healthcare resources. HMPV Causes While the exact causes of HMPV infections are not fully understood, several factors may contribute to its spread: Seasonal patterns: HMPV infections are more common during winter and early spring. Environmental factors: Crowded indoor spaces with poor ventilation can facilitate the spread of respiratory viruses like HMPV. Co-circulation with other pathogens: The simultaneous circulation of HMPV with other respiratory viruses, such as influenza and COVID-19, may complicate diagnosis and treatment. Genetic changes: Like all viruses, HMPV can mutate over time, potentially leading to more transmissible or virulent strains.
Read Article
Suvira Hospital is a leading multi-specialty facility in across India, providing world-class medical care using state-of-the-art technology. Our dedicated team of 10+ doctors specializes in oncology, cardiology, organ transplant, orthopaedics, and more. With Maximum operational beds and Multiple type diagnostics centres, we offer comprehensive and personalized healthcare to ensure the best possible outcomes for our patients. - Trusted by thousands of patients around the world each month. - With us, you pay the same price for healthcare as if you booked directly with the hospital. - Personalised healthcare solutions tailored to your individual needs. - Your own dedicated M1H Patient Specialist supporting you throughout your medical journey.
Read Article
Smoking and Your Cardiovascular Health According to the Food and Drug Administration (FDA), cardiovascular disease is one of the leading causes of death in the United States, accounting for about 800,000 deaths each year. Smoking cigarettes and using tobacco products is a habit responsible for nearly 20% of those deaths. While many people know that smoking and using tobacco products can harm your health, you may not understand the extent of the damage it can cause. The health experts outline some of the many ways that smoking and using tobacco products can harm your heart. Smoking Increases Your Risk for Heart Disease Atherosclerosis When you smoke, you’re actually changing the makeup of your blood and cause plaque to build up in your arteries. This plaque buildup can lead to the narrowing of your arteries, which is called atherosclerosis. When your arteries become narrowed, it's harder for your heart to pump oxygenated blood to other areas of your body. It can also create total blockages, leading to cardiac events like heart attack and stroke. Increased Stress on the Heart When you smoke cigarettes and use tobacco products, there is increased strain placed on your heart when it comes to pumping blood throughout your body. When you inhale cigarette smoke, you’re inhaling carbon monoxide—which continues to lower your oxygen levels, making your heart work harder to deliver oxygen where it’s needed. Changes to Your Blood Smoking cigarettes actually changes your blood and makes it become thicker and even sticky. Thicker and stickier blood is more difficult for your heart to pump throughout your body. It is also more prone to clotting, blocking blood flow and increasing your risk for heart attack and stroke.
Read Article

Suvira Hospital is a leading multi-speciality hospital in Jaipur, offering expert doctors, advanced treatments, emergency care, and diagnostics under one roof. Book your appointment today — Kyuki Har Ek Jaan Anmol.
